Flying Blind on Automation Spend: How US Enterprises Are Finally Confronting Their Cost Visibility Problem
There is a particular kind of organizational confidence that forms around automation investments shortly after deployment. A solution goes live, early efficiency metrics look promising, and leadership moves on to the next initiative. What rarely follows is a sustained, rigorous accounting of what that automation actually costs to keep running—month after month, year after year.
For a significant portion of US enterprises, this pattern has created a structural problem. Automation portfolios grow. Costs accumulate. And the financial picture that informed the original business case quietly diverges from reality. By the time the discrepancy becomes visible, organizations have often spent years operating on assumptions that no longer hold.
This is the automation audit gap: the space between what enterprises believe their intelligent systems cost and what those systems are actually consuming in licensing fees, maintenance labor, infrastructure overhead, and unplanned remediation.
The Anatomy of an Invisible Cost Structure
Understanding why this gap exists requires looking at how automation costs are typically categorized—and how easily those categories obscure the full picture.
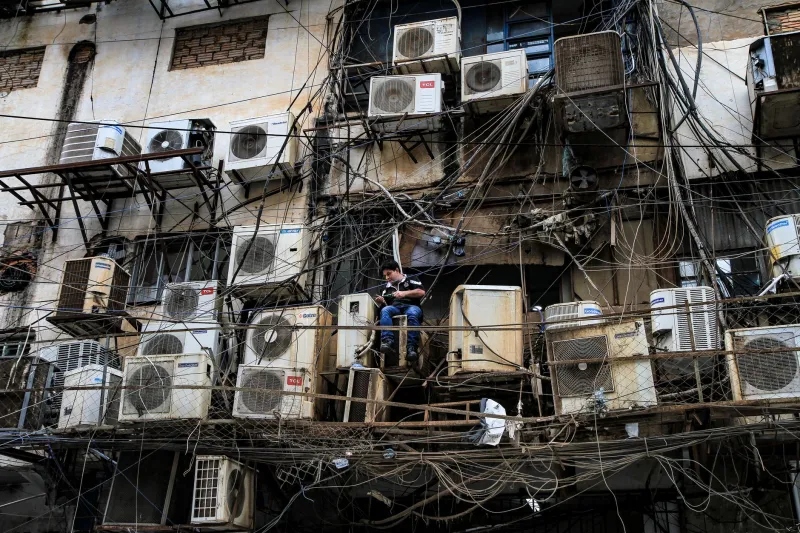
Most enterprise finance teams record automation-related expenses across multiple budget lines. Software licensing might sit under IT. Integration maintenance might fall under operations. Developer time spent on bot remediation might be absorbed into a general engineering allocation. When costs are this distributed, no single stakeholder owns the complete financial profile of an automation asset.
Compounding the problem is the nature of automation maintenance itself. Unlike physical infrastructure, which degrades in predictable and visible ways, software-based automation systems tend to fail at the seams—when upstream data formats change, when API dependencies shift, or when business process modifications render existing logic obsolete. These failure events generate reactive labor costs that are rarely attributed back to the automation system responsible for triggering them.
The practical effect is that organizations consistently undercount what their automation portfolios cost to sustain. Some internal analyses, once organizations finally conduct them, reveal that ongoing operational expenses represent anywhere from 30 to 60 percent of the total cost of ownership over a five-year horizon—a figure that rarely appears in the original ROI projections that justified the investment.
Why ROI Claims Go Unverified
The automation industry has, for years, operated on the strength of compelling ROI narratives. Vendors present case studies with impressive efficiency multipliers. Consulting partners build business cases anchored to labor hour reductions and error rate improvements. These projections are not necessarily dishonest—but they are almost universally forward-looking, and they are rarely subjected to rigorous post-deployment verification.
Part of the challenge is institutional. The teams responsible for building the ROI case are often not the same teams responsible for operating the system after it launches. The handoff creates an accountability gap. No one is formally tasked with returning to the original projections twelve or twenty-four months later and asking whether they materialized.
There is also a cultural dimension. Acknowledging that an automation investment is underperforming carries political risk within organizations where that investment was championed by senior leadership. The path of least resistance is to allow favorable early metrics to stand as the permanent record, rather than commission a more uncomfortable reassessment.
The result is a landscape where many US enterprises are operating automation solutions that have never been independently audited against their original financial promises.
Building a Cost-Transparency Framework
Organizations that are successfully closing the automation audit gap share a common approach: they treat cost visibility as an ongoing operational discipline rather than a one-time exercise.
The foundation of this approach is a unified automation asset register—a centralized inventory that documents not just what automation systems exist, but what each one costs across its full lifecycle. This means capturing direct software and licensing expenses, allocated infrastructure costs, maintenance labor (both planned and reactive), integration dependencies, and the organizational resources required to govern and update the system over time.
Building this register is not a trivial undertaking. It requires cooperation across IT, finance, operations, and the business units that own specific automation workflows. But enterprises that have completed the exercise consistently report that the resulting visibility changes how they make future investment decisions in fundamental ways.
Beyond the asset register, leading organizations are establishing what might be called automation cost governance cadences—structured review cycles, typically quarterly, in which automation portfolio costs are reconciled against current performance data. These reviews are designed to surface systems that are consuming disproportionate maintenance resources relative to the value they deliver, flagging them for remediation, replacement, or retirement before the financial drag becomes severe.
The Role of Intelligent Monitoring Tools
Manual auditing processes, while valuable, have inherent limitations in environments where automation portfolios span dozens or hundreds of discrete systems. Increasingly, US enterprises are turning to intelligent monitoring platforms that provide real-time visibility into automation performance and cost metrics simultaneously.
These tools work by instrumenting automation systems to emit telemetry data—execution logs, error rates, processing volumes, infrastructure utilization—and aggregating that data into dashboards that finance and operations leaders can actually interpret. When integrated with cost allocation systems, they enable organizations to generate unit economics for individual automation assets: what does it cost, per transaction processed or task completed, to operate this system today versus when it was first deployed?
The value of this capability extends beyond simple cost tracking. When performance degradation and cost escalation can be detected in near real time, organizations gain the ability to intervene before small inefficiencies compound into significant budget problems. Predictive cost modeling—projecting future maintenance burden based on current degradation trends—is an emerging capability that some platforms are beginning to offer, and it represents a meaningful advance in how enterprises can manage automation portfolios proactively.
Accountability as Infrastructure
Perhaps the most important shift that cost-transparent organizations make is a structural one. They assign explicit ownership of automation ROI accountability to a named function or role—whether that is an automation center of excellence, a dedicated automation finance analyst, or a cross-functional governance committee with a formal charter.
This accountability structure ensures that the question of whether an automation investment is performing as promised is never allowed to go unasked. It creates organizational memory around the original business case and establishes a mechanism for revisiting that case as operating conditions evolve.
For US enterprises navigating increasingly complex automation portfolios, this kind of structural accountability is no longer optional. The organizations that treat cost visibility as foundational infrastructure—rather than an afterthought—are the ones positioned to make automation investments that compound in value rather than quietly erode it.
The automation audit gap is not inevitable. It is a product of organizational choices. And it is one that enterprises can choose, deliberately and systematically, to close.